Market Review October 26: Pause in Oil, UST 10Y Yield Drops Below 5%, and Asia Falls Ahead of Central Bank Decisions
On Monday, October 26, 2026 (data as of 13:30 Almaty time / UTC+5), markets entered a key week of the year. Brent oil retreated to $114.5 per barrel after correcting from multi-month highs ($116.72), easing inflationary pressure
On Monday, October 26, 2026 (data as of 13:30 Almaty time / UTC+5), markets entered a key week of the year. Brent oil retreated to $114.5 per barrel after correcting from multi-month highs ($116.72), easing inflationary pressure and allowing gold to bounce back from the $4,000 level. The main triggers of the week are still ahead: the Fed decision on Wednesday, PCE inflation data on Thursday, and quarterly reports from Big Tech megacaps — Microsoft, Alphabet, and Amazon.
Commodities: Brent Pullback from $116.7 Peak and Gold Returns Above $4,000
Oil Correction: After the strongest week in 4 years (+6.2%), Brent prices pulled back to $114.5 (−1.9%). The main driver remains the reduction in global supply amid military escalation with Iran and tanker incidents in the Strait of Hormuz.
Gold Dynamics: Gold held the key threshold, supported by a direct link: falling oil eases inflation risks and gives treasury bonds a breather. A technical sideways range is expected between $3,946–4,032 ahead of Fed decisions.
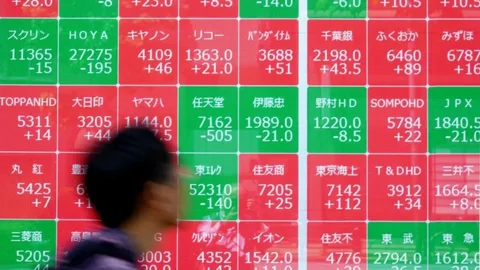
Asia: Korea Crash (−20% Monthly) and Big Tech Earnings Anticipation
Pressure on AI Sector: South Korea's KOSPI lost −1.5%, deepening its monthly decline to nearly 20%. Semiconductor giants remain at the center of turbulence. In China, investors watch the 5th Plenum of the CPC Central Committee for stimulus signals, while Hang Seng (+0.5%) and ASX 200 (+0.2%) trade in positive territory.
| Index / Exchange | Level / Close | Change for the Day |
|---|---|---|
| KOSPI (Seoul) | 5,469.47 | −1.50% |
| Nikkei 225 (Tokyo) | 62,189.65 | −0.80% |
| Hang Seng (Hong Kong) | 23,206.82 | +0.50% |
| Shanghai Composite | 3,697.52 | +0.20% |
| ASX 200 (Sydney) | 8,809.90 | +0.20% |
Focus on AI Profitability Proof: The market expects not general promises but clear capital return figures in reports from Microsoft, Alphabet, Amazon, SK Hynix, and Samsung Electronics.
Macro: Fed Decision, PCE Inflation, and UST 10Y Yield Pullback
Monetary Desk: The 10-year UST yield fell to 4.97% (40 bps below the October peak of 5.36%). On Wednesday, the market expects the Fed to keep rates at 3.75–4.00%, but will closely analyze Kevin Warsh's rhetoric regarding a December hike (priced in with 75–80% probability).
Super Week for Regulators: Besides the Fed, rate decisions will be made by the ECB, Bank of Japan, RBNZ, and Bank of England. On Thursday, key data on core PCE inflation for September (forecast 3.1%) and US Q3 GDP (+3.2%) will be released.
Main Events Calendar of the Week (UTC+5)
| Date / Time | Event / Release / Reporting | Status / Importance |
|---|---|---|
| Wed (28.10) 23:00 | US Fed Rate Decision and Press Conference / UK Budget / SK Hynix Reports | Critical |
| Thu (29.10) 17:30 | US PCE Index + Q3 GDP / ECB and Bank of Japan Meetings / Big Tech Reports | Critical |
| During the Week | Reports: Microsoft, Alphabet, Amazon, Intel, Boeing, Chevron, ExxonMobil | High |
| Tue (03.11) | US Midterm Elections / RBA Meeting | Key |
What Traders Should Watch:
- Two Points of Maximum Risk: The Fed decision on Wednesday (23:00) and PCE inflation on Thursday (17:30) come consecutively with Microsoft and Alphabet reports. Do not carry leveraged positions through these dates.
- Volatility of Oil Gaps: Brent price shifts from +3.1% on Friday to −1.9% today reflect heightened geopolitical tension ahead of the US elections on November 3.
- Strict Margin Limits: Considering weekly volatility ranges (gold ±2.6%, Nasdaq ±2.6%, oil ±3.8%), set a strict margin load limit at 50% of the deposit instead of the usual 70%.