US NFP Failure, Nikkei Soars to 3-Month Highs, and DXY Above 102: Market Highlights for October 5
On Monday, October 5, 2026 (data as of 14:00 Almaty time / UTC+5), markets open the week reacting to a disappointing US employment report (only 29K new jobs vs. 90K forecast). This reduced the likelihood of an October rate hike by the Fed and supported stock indices led by Japan's Nikkei (+2.4%).
On Monday, October 5, 2026 (data as of 14:00 Almaty time / UTC+5), markets open the week reacting to a disappointing US employment report (only 29K new jobs vs. 90K forecast). This reduced the likelihood of an October Fed rate hike and supported stock indices led by Japan's Nikkei (+2.4%). However, the paradox of the day is that the dollar (DXY 102.2) and US Treasury yields held multi-year highs due to European political risks.
USA: Weak NFP Removes Threat of October Rate Hike
Fed Expectations: Following weak employment data, the market prices in about an 80% chance of a pause at the October meeting, although the chance of a hike in December remains around ~69%. Two-year UST yields fell 10 bps to 4.78%, but the long end of the curve held at highs (10Y — 5.28%, 30Y — 5.63%).
Key Trigger: The main event of the week will be the release of the Fed meeting minutes (FOMC Minutes) on Wednesday, which will shed light on the balance of power within the Committee.
Asia and Currencies: Nikkei Rally (+2.4%) and Pressure on the Euro
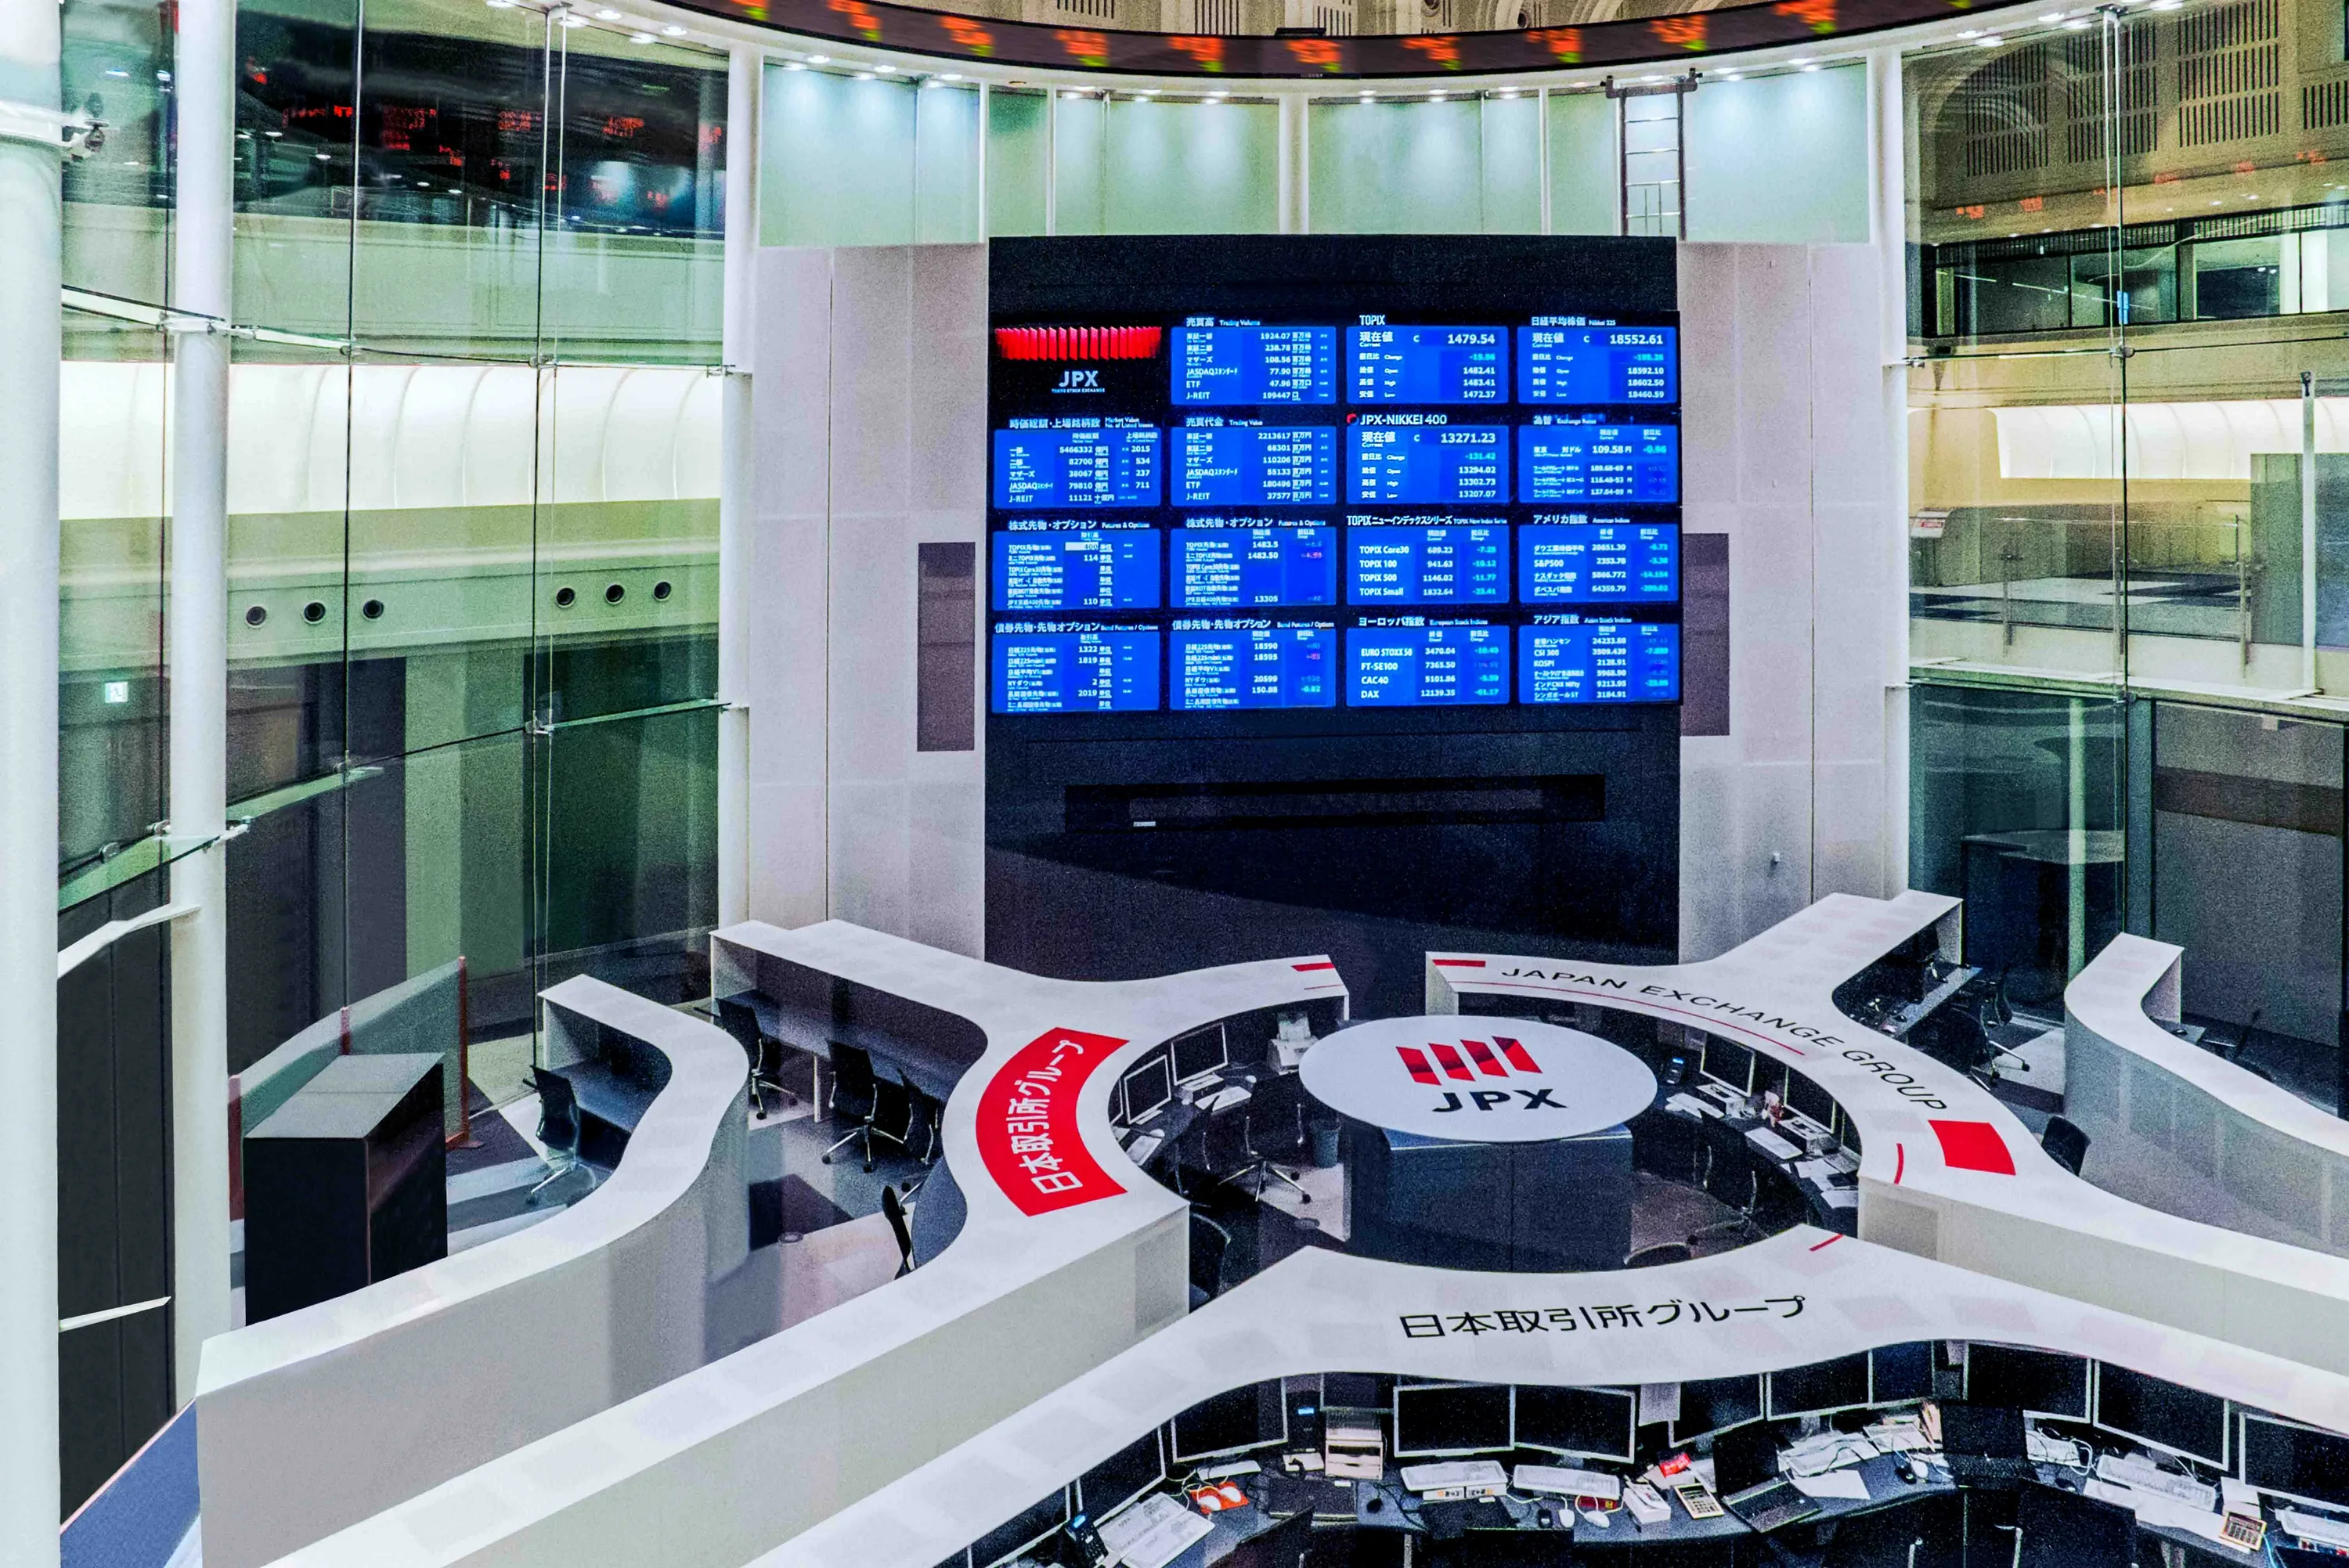
Records in Japan: The Nikkei 225 index rose to 69,947 amid a tech sector rally (Tokyo Electron +5.5%, Advantest +4.3%). BoJ Deputy Governor Uchida called AI a "positive demand shock," fueling rate hike expectations, but USD/JPY held around 158.
Europe at Risk: The EUR/USD pair dropped to 1.1191 (−0.56%), hitting a low not seen since May 2025. The euro is pressured by a political risk premium due to early elections in Spain and France's budget concerns.
| Pair | Current | Change Today | Fri Close |
|---|---|---|---|
| EUR/USD | 1.1191 | −0.56% | 1.1253 |
| GBP/USD | 1.3215 | −0.21% | 1.3243 |
| USD/JPY | ~158.00 | — | 157.67 |
Commodities: Abnormal Brent-WTI Spread at $12.3 and Metals Rebound
Oil Imbalance: Brent trades at $102.84 (+0.57%), while WTI is at $90.53 (−0.64%). The spread widened to an abnormal $12.3 due to a local diesel shortage and a discount from Saudi Aramco ($3 off Arab Light).
Metals and Crypto: Gold and silver are rebounding after last week's decline. Bitcoin rose above $86,000, following softer US rate hike expectations.
Calendar and Key Points (October 5, Almaty Time)
| Time | Event / Release | Actual / Status |
|---|---|---|
| Morning | Japan / Australia Services PMI | 51.3 / 51.9 (actual) |
| Mon–Tue | Fed and ECB Speakers' Speeches | Throughout the day |
| Wednesday | Fed Meeting Minutes (FOMC Minutes) | Key |
| Thursday | US Initial Jobless Claims | High |
Practical Takeaways for Traders:
- Unstable Decorrelation: Stocks rise on hopes of a Fed pause, but the bond market and DXY hold highs. Avoid aggressive stock purchases without confirmation from falling yields.
- Oil Anomalies: The Brent-WTI spread at $12.3 signals a temporary breakdown of standard arbitrage links — factor in risks from increased volatility.
- Preparation for Fed Minutes: Wednesday's minutes will be the main judge between stock bulls and dollar bulls. Keep risks under control.