Market Review September 7: Brent Storms $98 Amid Attacks in the Strait of Hormuz, Chipmakers Lift Asia
Global markets start the new week with mixed sentiment. Strong US employment data supported confidence in the economy's resilience but simultaneously revived expectations of a Fed rate hike. The main source of risk remains the Middle East.
Global markets start the new week with mixed sentiment. Strong US employment data supported confidence in the economy's resilience but simultaneously revived expectations of a Fed rate hike. The main source of risk remains the Middle East: new US and Iranian strikes on vessels near the Strait of Hormuz pushed Brent to a seven-week high. Asia is rising thanks to semiconductor manufacturers, Europe is declining due to inflationary and political risks, while gold and bitcoin are under pressure from high yields. US exchanges are closed today for Labor Day, so overall trading activity will be lower than usual.
USA: Market Awaits Inflation
Last session results: US indices closed lower due to strong labor market report. In August, the US economy added 162,000 jobs versus the expected 56,000, while unemployment remained at 4.1%.
Fed rate expectations: The market currently prices in about a 58% chance of a rate hike on September 16 and around 70% by the end of October. US main exchanges are closed today; futures market shows muted movement (S&P 500 -0.1%, Nasdaq +0.3%), as investors await fresh inflation data.
Europe: Oil and Politics Weigh on Market
Index and sector dynamics: The STOXX 600 index is down 0.1–0.3%, Swiss market fell 1.2%. The oil and gas sector rises 1.2% amid expensive oil, while pharma is under pressure: Novartis shares plunged 3.3% due to pelacarsen trial failure.
Politics and ECB: Uncertainty increased after Saxony-Anhalt elections where AfD gained about 44%. ECB meeting is on Thursday: the market expects a 25 bps rate hike to 2.75%, pricing in a 75% chance of another step to 3% by December.
Asia: Semiconductors Pull Market Up
Chip rally: Asian markets mostly trade higher: Nikkei 225 up 2.1%, KOSPI soared 4.6%, Shanghai Composite +0.1%, while Hang Seng lost 0.8%. Leaders were giants Samsung Electronics (+5.3%) and SK Hynix (+8.1%). Positivity was supported by Foxconn reporting record August revenue (+52% y/y).
Pressure on India: Indian indices (Nifty 50 -0.25%, Sensex -0.24%) declined: as an energy importer, rising energy prices pose risks of higher inflation and widening trade deficit.
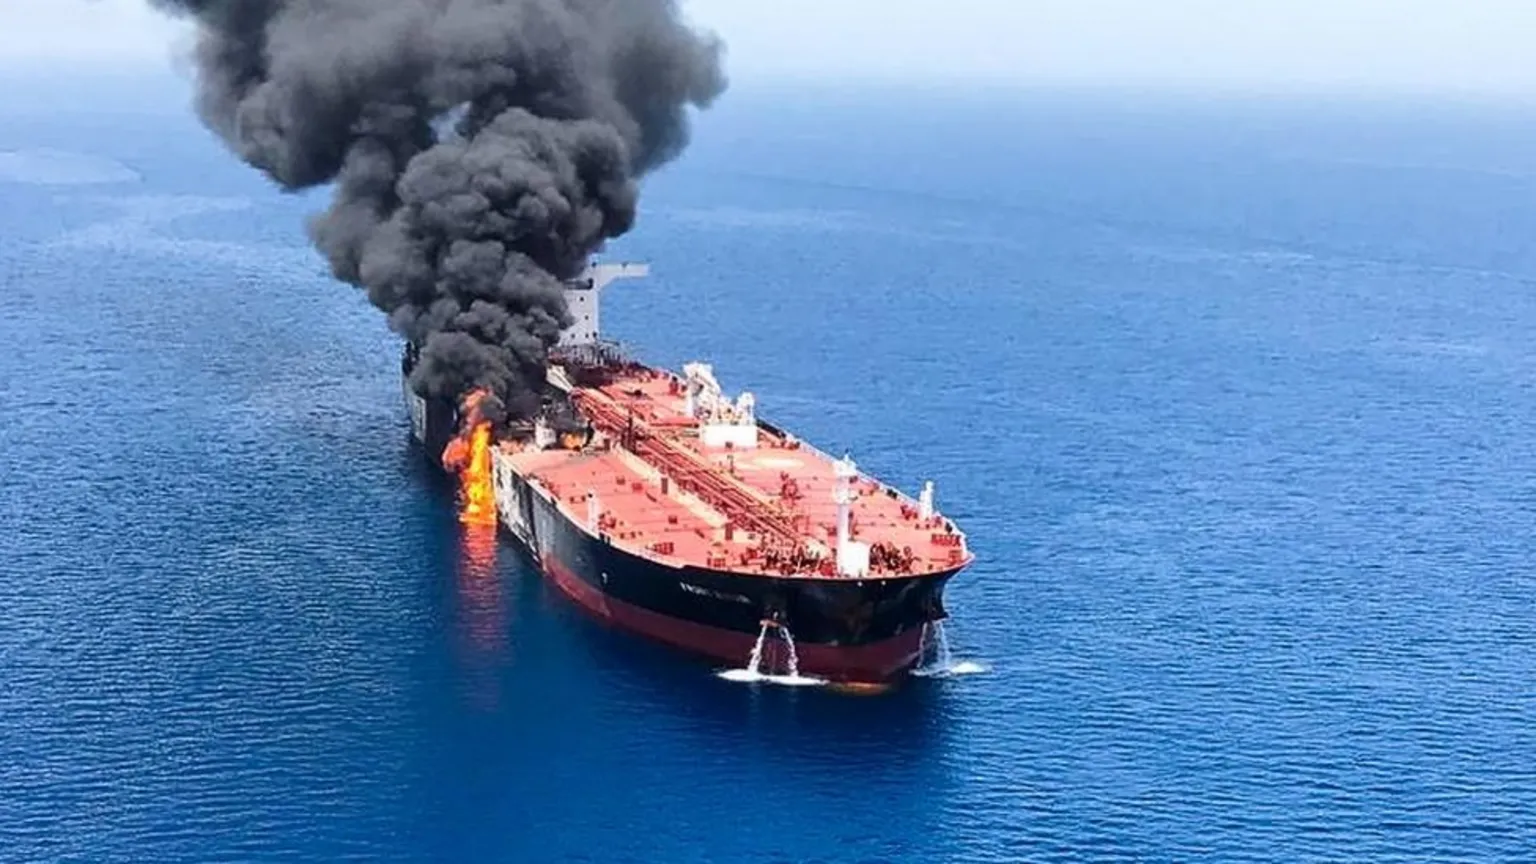
Oil: New Escalation Near the Strait of Hormuz
Quotes: Brent rose to a seven-week high — around $97.48 per barrel (+1.25%), WTI gained to $92.62 (+1.25%).
Escalation and risks: Over the weekend, US forces attacked three Iranian tankers; Iran announced retaliatory strikes on US vessels and route violators. Traffic through the Strait of Hormuz fell to a May low (10 vessels per day), while OPEC+ maintained quotas. Goldman Sachs allows for a Brent surge to $120 if escalation continues.
Gold, Currencies, Bonds, and Cryptocurrencies
Precious metals and bonds: Gold declined to $1,398.13 (-0.7%), silver dropped to $15.53 due to high US Treasuries yields (10-year around 4.78%), which deprive metals of interest income. DXY trades around 99.1, yen strengthened to 155.76 per dollar on expectations of a Bank of Japan rate hike.
Cryptocurrencies: Bitcoin fell 0.4% to $79,400 (range $79,100–80,500), Ethereum near $2,490. Negative background was the hack of a Liquid Network wallet with withdrawal of 4,000 BTC ($320 million), presumably by "white hat" hackers.
Main Events of the Week
After a quiet Monday, investors face a key week ahead of September meetings of global regulators.
| Date | Event |
|---|---|
| September 10 | ECB interest rate decision; US PPI index; Oracle earnings report |
| September 11 | US Consumer Price Index (CPI) |
| September 15–16 | US Federal Reserve interest rate meeting |
| September 17–18 | Bank of Japan meeting |
Summary: Today markets are divided: the tech sector rises on semiconductors, while geopolitics and oil above $97 weigh on European stocks and gold. The main risk is Brent breaking $100, which would accelerate inflation expectations. Until the US CPI release on Thursday, cautious trading and localized volatility are most likely.