Market Review October 29: Microsoft Rises 3% and Alphabet Falls 10%, KOSPI Rally at 6.6%, and PCE Anticipation
On Thursday, October 29, 2026 (data as of close on October 28 and morning of October 29, Almaty / UTC+5), markets digest the results of the Fed meeting. The rate was held at 3.75–4.00%, but two committee members (Lisa Cook and Beth Hammack) voted
On Thursday, October 29, 2026 (data as of close on October 28 and morning of October 29, Almaty / UTC+5), markets are digesting the results of the Fed meeting. The rate was held at 3.75–4.00%, however two committee members (Lisa Cook and Beth Hammack) voted for an immediate 25 bps hike. The market prices in about an 85% chance of a rate increase on December 9. The AI sector showed a clear split: Microsoft (+3%) pleased investors with cloud growth, while Alphabet (−10%) plunged due to negative cash flow.
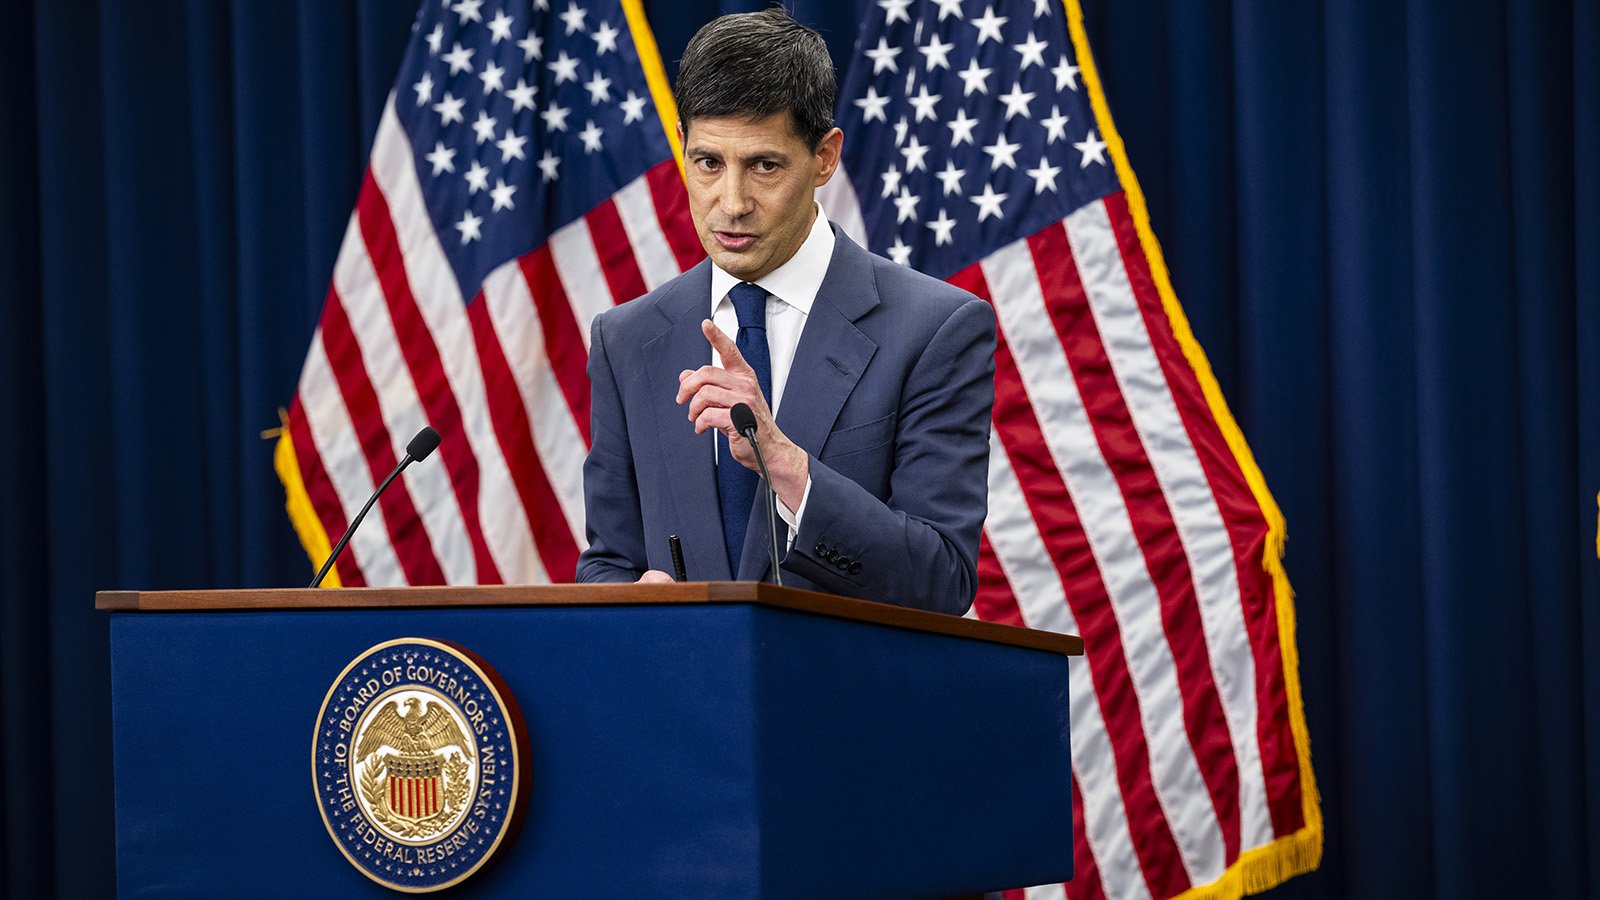
US Fed: Pause 10 vs 2 and UST 10Y Yield Above 5.02%
Committee split: The demand for an immediate rate hike by two governors sent a hawkish signal. Chairman Kevin Warsh described the discussion as a "serious family quarrel," leaving the December meeting completely open. Against this backdrop, 10-year Treasury yields settled above 5.02%, and the Bank of Canada yesterday raised its rate by 25 bps to 2.50%.
Currency desk: The US dollar stabilized (DXY ~102.14–102.20), maintaining strength against the euro (1.1141) and yen (157.84) ahead of the ECB decision.
Stocks: Disparity Between Microsoft and Alphabet, KOSPI Rally (+6.6%)
Big Tech gap: Azure growth of 48% lifted Microsoft by +3%, confirming AI profitability. Alphabet, on the contrary, plunged −10% due to negative free cash flow (−$9.07 billion). In Asia, South Korea's KOSPI showed phenomenal growth of +6.6% following SK Hynix's report.
| Index / Exchange | Level / Close | Change for the Day |
|---|---|---|
| KOSPI (Korea) | 6,012.44 | +6.60% |
| S&P 500 (USA) | 7,744.00 | +0.28% |
| Nasdaq Composite (USA) | 26,550.00 | +0.27% |
| Microsoft / Alphabet | Reaction to reports | +3.0% / −10.0% |
| DAX 40 (Europe) | 25,591.00 | +0.71% |
Evening expectations: Today, market attention will shift to the earnings reports of Amazon, Intel, Mastercard, and Caterpillar.
Commodities: Brent Reverses to $115.32, Gold Squeezed, and BTC Holds Firm
Energy momentum: Oil returned to growth (Brent ~$115.32, WTI +$2.88 to $102.78) due to failed talks in Tehran. The Fed hawks cite expensive fuel as a key factor. Ahead is the OPEC+ meeting on November 1.
Precious metals and crypto: Gold is held back by resistance at $4,074 amid rising yields. Bitcoin holds the $81,000 level, but institutional inflows into spot ETFs remain close to zero since the start of the year.
Main Events Calendar (Oct 29–30, UTC+5)
| Date / Time | Event / Release / Reports | Status / Importance |
|---|---|---|
| 29.10 (17:30) | US PCE Index (Prog. Core +3.1% YoY) + Q3 GDP + Jobless Claims | Critical |
| 29.10 (18:15 / 18:45) | ECB Rate Decision + Press Conference by C. Lagarde | Critical |
| 29.10 (Night) | Quarterly Earnings: Amazon and Intel | High |
| 30.10 (Morning) | Bank of Japan Rate Meeting | High |
What Traders Should Watch:
- Peak risk at 17:30: Releases of PCE, US GDP, and jobless claims come out within one minute. Spreads will widen, and strong stop order slippage is possible.
- Double news window (17:30 — 18:15): US data and ECB decision are published 45 minutes apart. Open positions face cross-risk.
- Gold asymmetry: Exceeding the PCE forecast will hit gold via the dollar and yields (targets — $4,000 and $3,975). The upside bounce is limited by nearby resistance at $4,074.