Market Review October 20: Brent at 5-Month High, Korea's Decline, and Netflix Report Anticipation
On Tuesday, October 20, 2026 (data as of 15:00 Almaty time / UTC+5), Wall Street's tech rebound was overshadowed by a new crash in Asia: South Korea's KOSPI plunged 4.3%. The key macro factor remains Brent oil soaring to $110 due to
On Tuesday, October 20, 2026 (data as of 15:00 Almaty time / UTC+5), Wall Street's tech rebound was overshadowed by a new crash in Asia: South Korea's KOSPI plunged 4.3%. The key macro factor remains Brent oil soaring to $110 due to strikes on Saudi infrastructure and tensions in the Strait of Hormuz. This supports high Treasury yields and puts pressure on gold assets and AI sector valuations.
Commodities: Oil at 5-Month High ($110) and Calm in Gold
Energy driver: Brent prices jumped to $109.5–110.0 per barrel following attacks on Saudi oil facilities and incidents in the Strait of Hormuz. In Europe, natural gas trades around €90/MWh — the highest since December 2022.
Precious metals paradox: Gold remains lackluster below $4,135: high real yields on Treasury bonds (UST 10Y ~5.12%) offset its status as a "safe haven" metal.
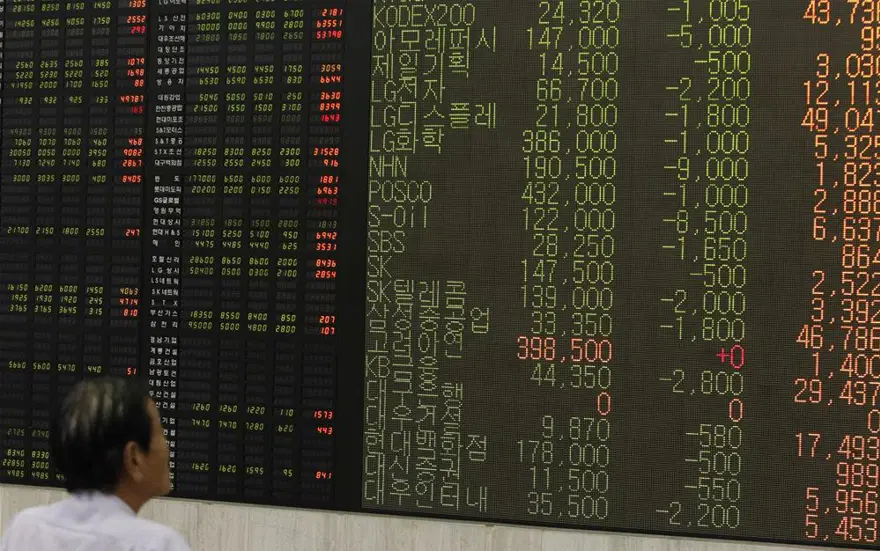
Stock Markets: KOSPI Crash (−4.3%) and Decoupling from Wall Street
Shock in Asia: Despite yesterday's Nasdaq rebound (+1.11%), the Asian session was marked by sell-offs. Samsung and SK Hynix fell on demands for memory price cuts, while a weak debut by data center operator Elice worsened concerns about AI infrastructure financing costs.
| Index / Exchange | Level / Close | Change for the Day |
|---|---|---|
| KOSPI (Korea) | ~5,521 | −4.30% |
| Nikkei 225 (Japan) | ~63,980 | −1.40% |
| Hang Seng (Hong Kong) | ~23,876 | −1.30% |
| DAX 40 (Europe, Mon) | 25,304 | −1.24% |
| Nasdaq Composite (USA, Mon) | 26,430.89 | +1.11% |
Europe under pressure: The French-German 10Y yield spread widened to 148 bps due to political tensions in France. US futures trade mixed ahead of the session (Nasdaq 100 −0.46%).
Macro and Fed: Pressure from Hot CPI and NAHB Housing Index Drop
Trajectory reassessment: September inflation (3.7% YoY) keeps the market on edge. The Fed meeting on October 28 is likely to hold rates steady (hike chance ~15%), but three tightening steps are priced in through mid-2027.
Signal from housing sector: US homebuilder sentiment (NAHB) plunged to 29 points — the lowest since June 2012, confirming developers' vulnerability to high rates.
Triggers and Earnings Calendar (October 20, Almaty Time)
| Time | Event / Release | Status / Importance |
|---|---|---|
| 17:15 | ADP Employment Report (USA) | High |
| 17:30 | US Housing Starts for September (forecast 1.30 mln) | Medium |
| ~01:15 (Oct 21) | Netflix Quarterly Report (sets the tone for the week) | Critical |
| Wednesday | Big Tech Earnings: Meta, Tesla, IBM, Lam Research | Key |
What Traders Should Watch:
- Oil dominance: Brent holding above $108 pushes inflation expectations and yields higher, restraining rotation into growth stocks and gold.
- Asia-US divergence: Deep drop in Korea (−4.3%) despite Nasdaq gains creates risk of evening gaps. Avoid excessive leverage ahead of Netflix, Meta, and Tesla earnings releases.
- YouTrade discipline: Volatility in index CFDs (especially US100) significantly exceeds normal. Limit margin exposure (up to 70%) and avoid opening positions before the Netflix report.