Explosive $1 Billion Inflow Pushes Bitcoin to Year-to-Date Highs: Market Analysis for September 23
On Wednesday, September 23, 2026 (data as of 07:00 GMT), global markets are reacting to geopolitical easing: Donald Trump announced successful talks with Iran at the UN General Assembly. Brent crude settled below $100 per barrel, supporting the market backdrop.
On Wednesday, September 23, 2026 (data as of 07:00 GMT), global markets are reacting to geopolitical easing: Donald Trump announced successful talks with Iran at the UN General Assembly. Brent crude settled below $100 per barrel, supporting the stock market. Nasdaq closed at a historic high for the second day in a row, and Bitcoin soared to $87,000 — the highest level since January. However, the banking sector remains under pressure due to the Fed's hawkish stance.
Oil and Geopolitics: Brent Below $100 After Signals from New York
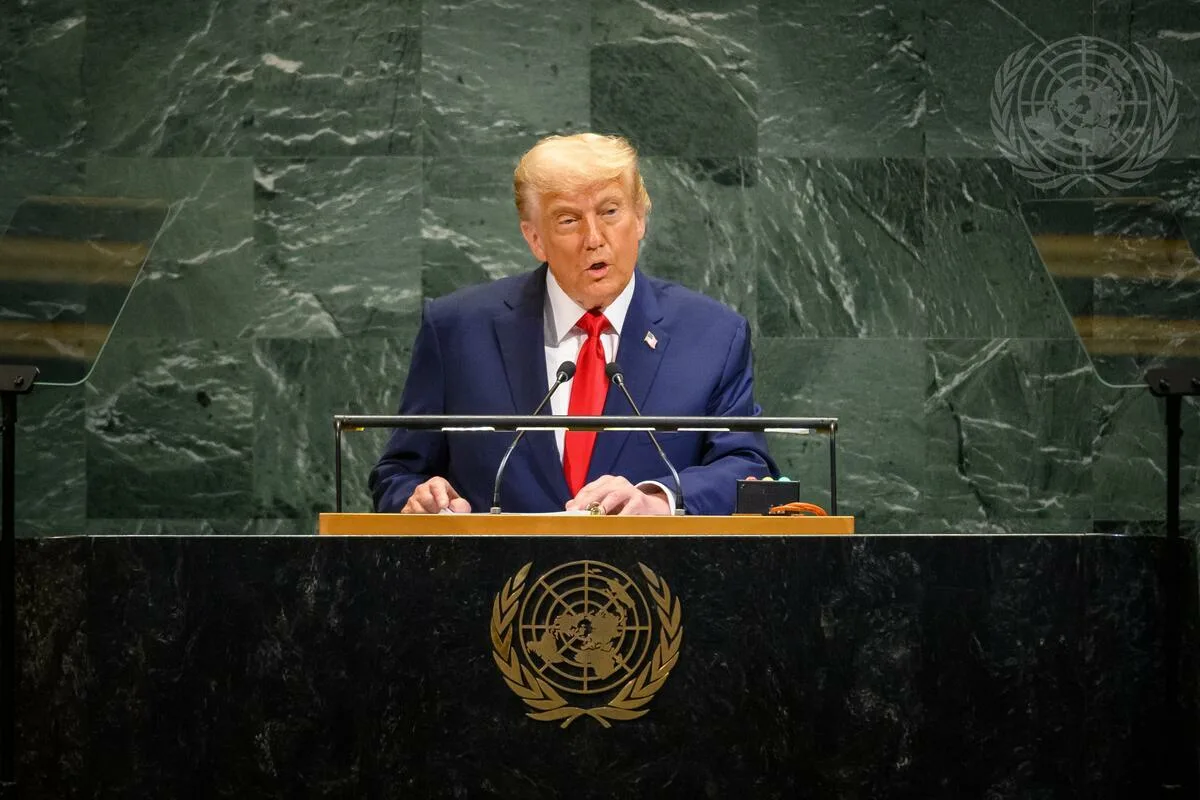
Diplomatic breakthrough: Donald Trump stated that the meeting between US and Iranian representatives at the UN General Assembly went "very well," offering Tehran a choice between a deal and a military scenario. The market reduced risk assessments of supply disruptions.
Price dynamics: Brent dropped to $98.40 per barrel (a week ago quotes approached $110). Cheaper fuel reduces inflation concerns but remains significantly above the pre-crisis $72.
Stocks: Nasdaq's Second Record and Sector Divergence
USA: Nasdaq Composite hit new highs for the second day in a row (+0.45%, to 27,244.28) driven by the AI sector. However, the S&P 500 remained flat (7,764.64), and the Dow Jones fell −0.36% due to bank sell-offs (JPMorgan −3.4%, Bank of America −3.0%).
Europe: Indices closed higher thanks to tech giants (ASML and Infineon up to +2.5%), but gains were limited by weakness in the financial sector (Allianz −3.4%, AXA −2.0%).
Asia: Mixed dynamics. KOSPI (+0.5%) and Taiex (+0.6%) rose, while Hong Kong (−0.8%) and Shanghai (−0.4%) declined. Tokyo markets were closed for holidays.
Rates and Currencies: 90% Probability of Fed Rate Hike Expected
Monetary policy: Traders price in a 90% chance of another Fed rate hike in December. The 10-year Treasury yield holds near 4.95%. The Richmond Fed manufacturing index fell to −2.
Currency market: The dollar continues to advance. EUR/USD dropped to 1.1427 (−0.2%), while USD/JPY rose to 157.59 (+0.1%).
Precious metals: Gold fell to $4,331.73 (−0.75%) under pressure from a strong dollar. Demand in Asia supports prices — China's imports have already exceeded 1,000 tons since the start of the year.
Cryptocurrencies: Bitcoin Rises to $87,000
Resistance breakthrough: Bitcoin broke out of the $80,000–82,000 range and soared to $87,000 (the highest since January 2026).
- ETF inflows: Spot ETFs attracted $999 million in one day (BlackRock, Fidelity, ARK 21Shares).
- Institutions: MicroStrategy purchased an additional 950 BTC ($75.7 million).
- Liquidations: Cascade of short position closures worth hundreds of millions of dollars.
Despite the rally, the main cryptocurrency is still about 31% below its all-time high ($126,080) recorded in October 2025.
Main event of the day: Preliminary PMI for September
During the release of key macroeconomic data, a blackout period applies (±3 minutes). Opening, closing, and editing order parameters are unavailable during this time.
| Region | PMI Forecasts |
|---|---|
| Eurozone | Manufacturing: 53.3 (vs 52.7). Services: 51.4 (vs 51.6). |
| United Kingdom | Values expected to remain around August's 52.5. |
| USA | Manufacturing: 53.6. Services: 56.0. |
Summary: This material is for informational purposes only and is not investment advice. Market focus today is on the PMI indices block, and tomorrow on the US-China summit.