Historic Dow Surge +3.03%, Brent Oil Crash Below $95, and Gold Rally to $4,134
On Thursday, November 5, 2026 (data as of 12:30 Almaty time / UTC+5), markets experienced a major reassessment of political risks. The Dow Jones surged +3.03% (best day post-election in 44 years), while Brent oil plunged nearly 9%.
On Thursday, November 5, 2026 (data as of 12:30 Almaty time / UTC+5), markets underwent a major reassessment of political risks. The Dow Jones index soared +3.03% (the best day post-election in 44 years), while Brent oil plunged nearly 9% to $93.99 per barrel amid expectations of a diplomatic de-escalation of the Iranian conflict. Meanwhile, gold jumped above $4,130, weakening the dollar index (DXY 101.26), but Asian chipmakers collapsed (KOSPI −6.1%) on fears of tighter AI regulation by the new US Congress.
US Stocks: Historic Dow Surge (+3.03%) and Big Tech Triumph
Political backdrop reassessed: The Democrats’ victory in both chambers created a political deadlock, eliminating risks of radical reforms. The Dow added 1,569 points, and market giants showed notable gains (Amazon +7.2%, Microsoft +7.1%, Apple +6.3%). Meanwhile, energy (ExxonMobil −4.6%) and defense (Lockheed Martin −6.9%) sectors declined amid reduced military risk.
Europe caught the momentum: Germany’s DAX (+2.22%) and Spain’s IBEX 35 (+3.00%) closed Wednesday with strong gains, reflecting the easing of global uncertainty factors.
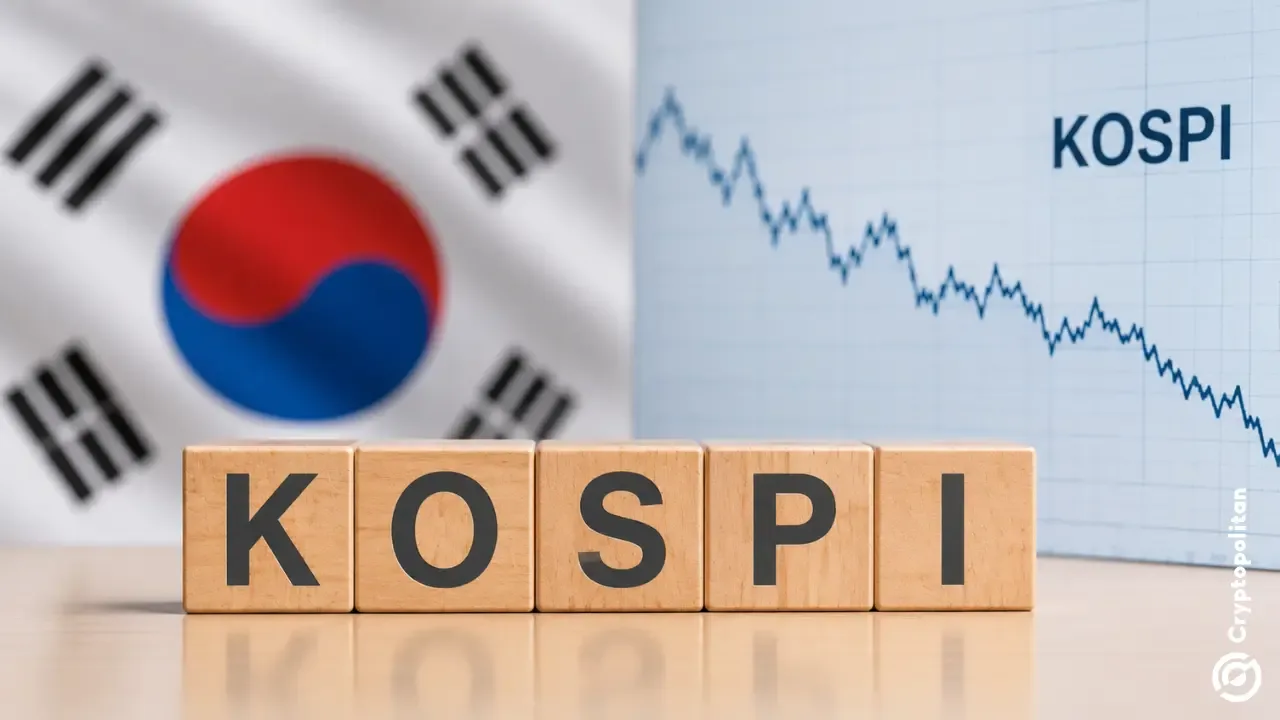
Asia: KOSPI Crash (−6.1%) and Chip Sector Rout
Regional split: Unlike gains in Hong Kong (+3.4%) and Australia (+2.6%), Asian chipmakers faced a wave of selling. The market is pricing in regulatory hurdles for AI infrastructure investments from the new US Congress, leading to a deep slump in regional tech giants.
| Index / Stock | Current Level | Change for the Day |
|---|---|---|
| KOSPI (Korea) | 5,339.00 | −6.10% |
| Samsung Electronics | Seoul | −5.70% |
| SK Hynix / Tokyo Electron | Korea / Japan | −7.4% / −7.7% |
| Hang Seng (Hong Kong) | 24,734.00 | +3.40% |
| Nikkei 225 (Tokyo) | 61,202.00 | −1.60% |
Supply chain imbalance: The disparity between the rally of US tech names (+4…7%) and the crash of Asian chipmakers (−6…9%) creates a temporary anomaly that requires correction.
Commodities and Metals: Brent Falls Below $95, Gold Soars to $4,134
Oil crash: Brent plunged −8.67% to a 2-month low ($93.99). The market believes the divided Congress reduces the likelihood of escalation against Iran. Gold, amid a falling DXY (101.26) and declining UST 10Y yields (4.89%), soared to $4,134.83 (+1.9%).
Labor market and Crypto: The US ADP employment report showed 86K (vs. 67K forecast), confirming economic resilience and leaving a 79–82% chance of a Fed hike in December. Bitcoin bounced back to $80,476.
Key Releases Calendar (Nov 5–6, UTC+5)
| Date / Time | Event / Publication / Reports | Status / Importance |
|---|---|---|
| 11/05 (17:00) | Bank of England Rate Decision (Forecast: 3.75% → 4.00%) | Critical |
| 11/05 (18:30) | US Initial Jobless Claims (Forecast ~196K) | Medium |
| 11/06 (18:30) | US Non-Farm Payrolls Report for October (Consensus 65K) | Main Trigger |
| 11/10 (Tuesday) | US Consumer Inflation (CPI) Release for October | High |
What Traders Should Watch:
- NFP report test on Friday: Tomorrow’s US employment report (18:30 Almaty) will be decisive for the dollar and gold. A strong report will confirm the Fed’s tightening scenario in December, while a weak one will continue the precious metals rally.
- Extreme oil risk: Brent moves of 8–9% per session require halving position sizes in energy relative to standard trading volume.
- YouTrade discipline: Maintain margin utilization no higher than 50%. Volatility remains elevated around the Bank of England decision and ahead of the NFP release.