19-Year Shock in the Debt Market: US Rates Above 5.2%, Mortgage at 7.37%, and Oil in Turmoil!
On Friday, September 25, 2026 (data as of 07:20 GMT), markets are experiencing historic pressure in the debt market: the yield on 10-year US Treasuries rose to 5.20% (the highest since 2007), and 30-year yields reached 5.50% (peak since 2004). Mortgag
On Friday, September 25, 2026 (data as of 07:20 GMT), markets are experiencing historic pressure in the debt market: the yield on 10-year US Treasuries rose to 5.20% (the highest since 2007), and 30-year yields reached 5.50% (peak since 2004). Despite the surge in US mortgage rates to 7.37%, the stock market is holding off a crash thanks to news of negotiations on a deal around the Strait of Hormuz. Tokyo is rising for the fifth consecutive session, while Hong Kong is falling for the third day.
Bonds: UST Yield Breaks 5.2% — 19-Year High
Pressure on the economy: The debt market has become the main source of the storm. The combination of strong macro data and expensive energy fuels inflation expectations. The Philadelphia Fed President stated the likely need for "additional tightening," and the market prices in a 67% chance of a Fed rate hike in October.
Effect on consumers: The 30-year mortgage rate in the US jumped to 7.37% — the highest in over two years, creating a direct cooling effect on the real estate market.
Stocks: Calm on Wall Street and Record Concentration
USA: The market closed near flat (S&P 500 −0.0%, Nasdaq +0.0%). Meta rose +4% on the announcement of the AI agent Muse, Oracle fell due to a data center force majeure, and MGM Resorts plunged −10%. The combined weight of Apple and Nvidia in the S&P 500 exceeded 15% — a historic record for capitalization concentration.
Europe: STOXX 600 lost −0.5% following the IT sector (Infineon −4.2%). A bright exception was Dior (+16%) amid a buyback offer by the Arnault family at €469.
Asia: Nikkei 225 gained +1.3% (66,384) thanks to the banking and tech sectors (Mizuho +4.36%, Tokyo Electron +4.51%). Hong Kong fell for the third day (Hang Seng −1.7%, Xiaomi −3.4%). Chinese and Korean exchanges are closed for holidays.
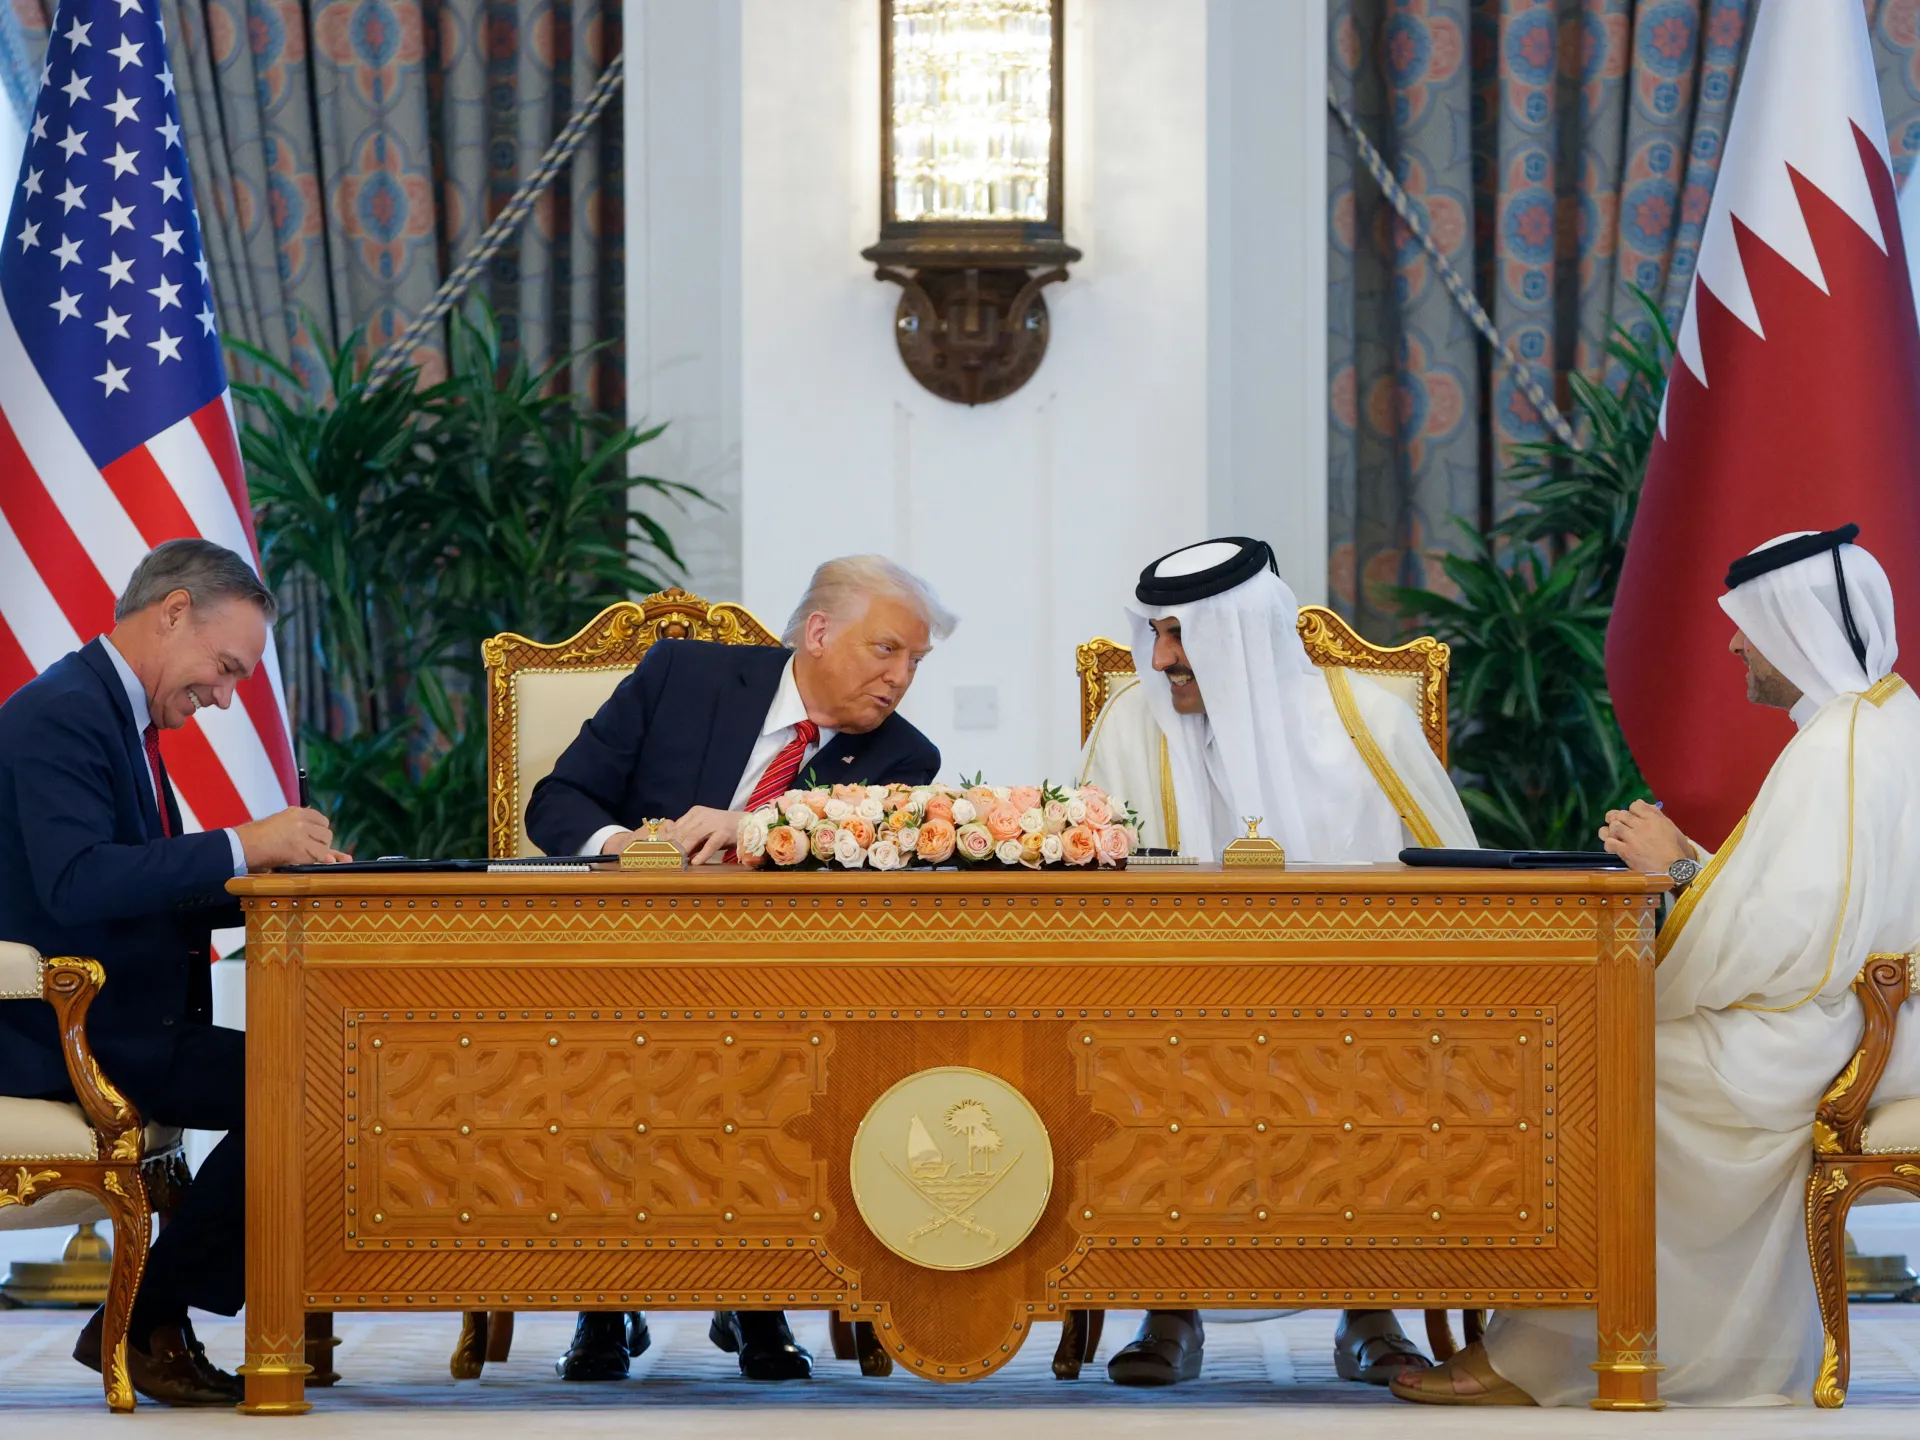
Commodities and Politics: Iran Talks and US–China Truce
Strait of Hormuz: Brent crude trades near $105.93 (−0.6%). The US and Iran, mediated by Qatar, are discussing a phased deal to lift the blockade of the strait. However, tensions remain high: only 10 vessels passed through the strait in 24 hours, and Saudi Arabia's production fell to the lowest since 1990.
US-China Trade: The US Treasury announced an agreement to extend the trade deal for 2 months. Official Beijing has not yet confirmed.
Gold: Stalled at $4,273 (−0.04%), losing about 7% over the month. The main drag on the metal is the high cost of holding it amid 5% yields on risk-free bonds.
Key Macroeconomic Data for Friday
During the release of major macroeconomic data, a blackout window rule applies (±3 minutes). Opening, closing, and editing order parameters during this period are unavailable.
| Time / Region | Indicator / Event |
|---|---|
| USA | Durable Goods Orders. |
| USA | University of Michigan Consumer Sentiment Index. |
Summary: This material is for informational purposes only and is not investment advice. Traders' main focus before the week’s close is on progress in Qatar’s negotiations over the Strait of Hormuz and data from the Michigan Institute.