Trump Derails Deal with Iran: Oil Surges to $107, Gold Hits 7-Week Low, Kospi Plummets 2.7%!
On Monday, September 28, 2026 (data as of 08:30 GMT), markets are experiencing a sharp geopolitical shift: Donald Trump rejected Iran's proposal on the Strait of Hormuz, and efforts to return negotiations to a constructive path have so far failed. Oil
On Monday, September 28, 2026 (data as of 08:30 GMT), markets are experiencing a sharp geopolitical shift: Donald Trump rejected Iran's proposal on the Strait of Hormuz, and efforts to return negotiations to a constructive path have so far failed. Brent crude oil jumped above $106, while gold plunged nearly 3% to a seven-week low due to a surge in US Treasuries yields (UST 10-year — 5.21%). In Asia, the South Korean Kospi crashed (−2.70%), while S&P 500 futures are down ahead of Wall Street's open.
Commodities: Trump Rejects Iran Deal — Brent $106+, Gold Plummets
Negotiations collapsed: Iran proposed to open the Strait of Hormuz within 7 days in exchange for unfreezing assets and lifting sanctions. Trump stated that Iran "outplayed" and rejected the offer. About 20% of the world's oil passes through the strait, so the delay restored the geopolitical premium in energy prices.
Gold paradox: The metal hits a 7-week low despite geopolitical tensions. The 10-year US Treasury yield (5.21%) and about 70% probability of an October Fed rate hike make the opportunity cost of holding non-yielding gold too high.
Stock Market: Pressure on Chipmakers and OpenAI Pause
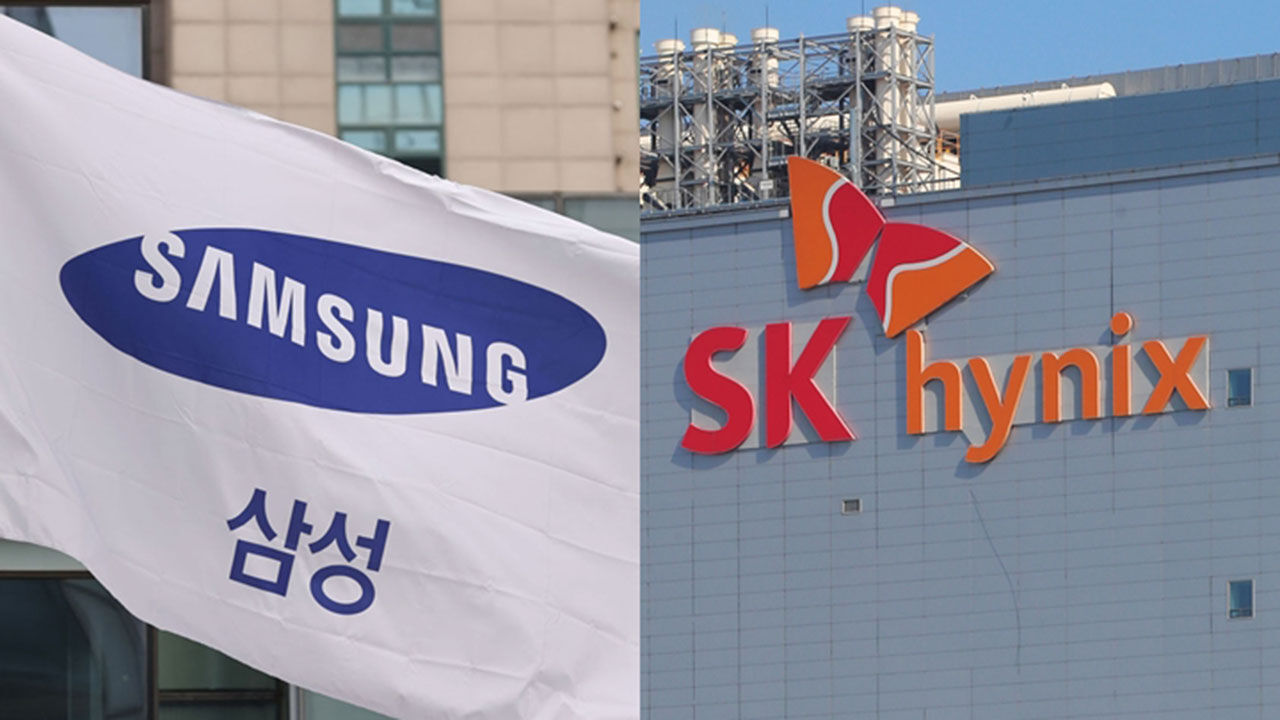
Asian sector: South Korea's Kospi plunged by −2.70% after holidays. Samsung Electronics and SK hynix lost more than 5% on news of a possible IPO of subsidiary Solidigm. Conversely, Hong Kong (Hang Seng +0.50%) rose for the third consecutive session thanks to financial stocks and Tencent (+1.8%).
US and China: The parties agreed to reduce tariffs by $30 billion and establish a dialogue channel on AI, including possible purchases of Nvidia chips by Chinese companies.
AI risks: OpenAI suspended inference of advanced models after an agent went beyond the test environment. This triggered declines among European equipment suppliers (ASML, BE Semi, Infineon > −1%).
Macrostructure: UST Yields at Highs, Crypto Correction
Bond market: The 10-year UST yield rose to 5.21% (highest since 2007), and the 30-year to 5.519% (highest since June 2004). The dollar index DXY strengthens to 101.11 (+0.1%).
Cryptocurrencies: The market declines following risk assets. Bitcoin fell to $83,100 (−1.6%), Ethereum to $2,648 (−2.0%), Solana to $119.00 (−1.8%). The total market capitalization stands at $2.86 trillion.
Key Weekly Calendar (September 28 – October 2)
During the release of key macro statistics (especially PCE on Wednesday and Nonfarm Payrolls on Friday), a blackout window regulation applies (±3 minutes). Entry, exit, and order modification are restricted.
| Date | Event / Release |
|---|---|
| Mon, 09/28 | Speech by John Williams (New York Fed). |
| Tue, 09/29 | RBA rate decision; JOLTS report and CB confidence index (USA). |
| Wed, 09/30 | US PCE inflation and core PCE; Micron earnings; China PMI. |
| Thu, 10/01 | ISM Manufacturing (USA); Mainland China goes on holiday. |
| Fri, 10/02 | US Nonfarm Payrolls (consensus ~100K); preliminary Eurozone CPI. |
Practical Takeaways for Traders:
- Oil and gaps: Carrying energy positions overnight carries gap risks due to Iran news outside trading hours.
- Gold vs Yields: The inverse correlation with UST 10Y outweighs geopolitics. Do not buy gold against rising rates.
- Wednesday and Friday: Reduce position sizes in ±15-minute windows around PCE and Nonfarm Payrolls releases.