Market Overview September 1: Brent Breaks $91, US Treasuries Yield Hits January 2025 High, Markets Await US Employment Data
Today, September 1, 2026, global markets start the new month in a tense mode. The resumption of direct attacks between the US and Iran has brought back the geopolitical premium to energy prices: Brent rose above $91 per barrel, and the movement
Today, September 1, 2026, global markets begin the new month in a tense mode. The resumption of direct attacks between the US and Iran has brought back the geopolitical premium to energy prices: Brent rose above $91 per barrel, and vessel traffic through the Strait of Hormuz remains extremely limited. The rise in oil has intensified concerns about a new wave of inflation, causing investors to sell government bonds; the yield on 10-year US Treasuries reached its highest level since January 2025, and the probability of a Fed rate hike in September exceeded 65%. Stock markets are reacting cautiously: energy companies are rising, while rate-sensitive sectors are under pressure.
USA: Wall Street Closed August Lower
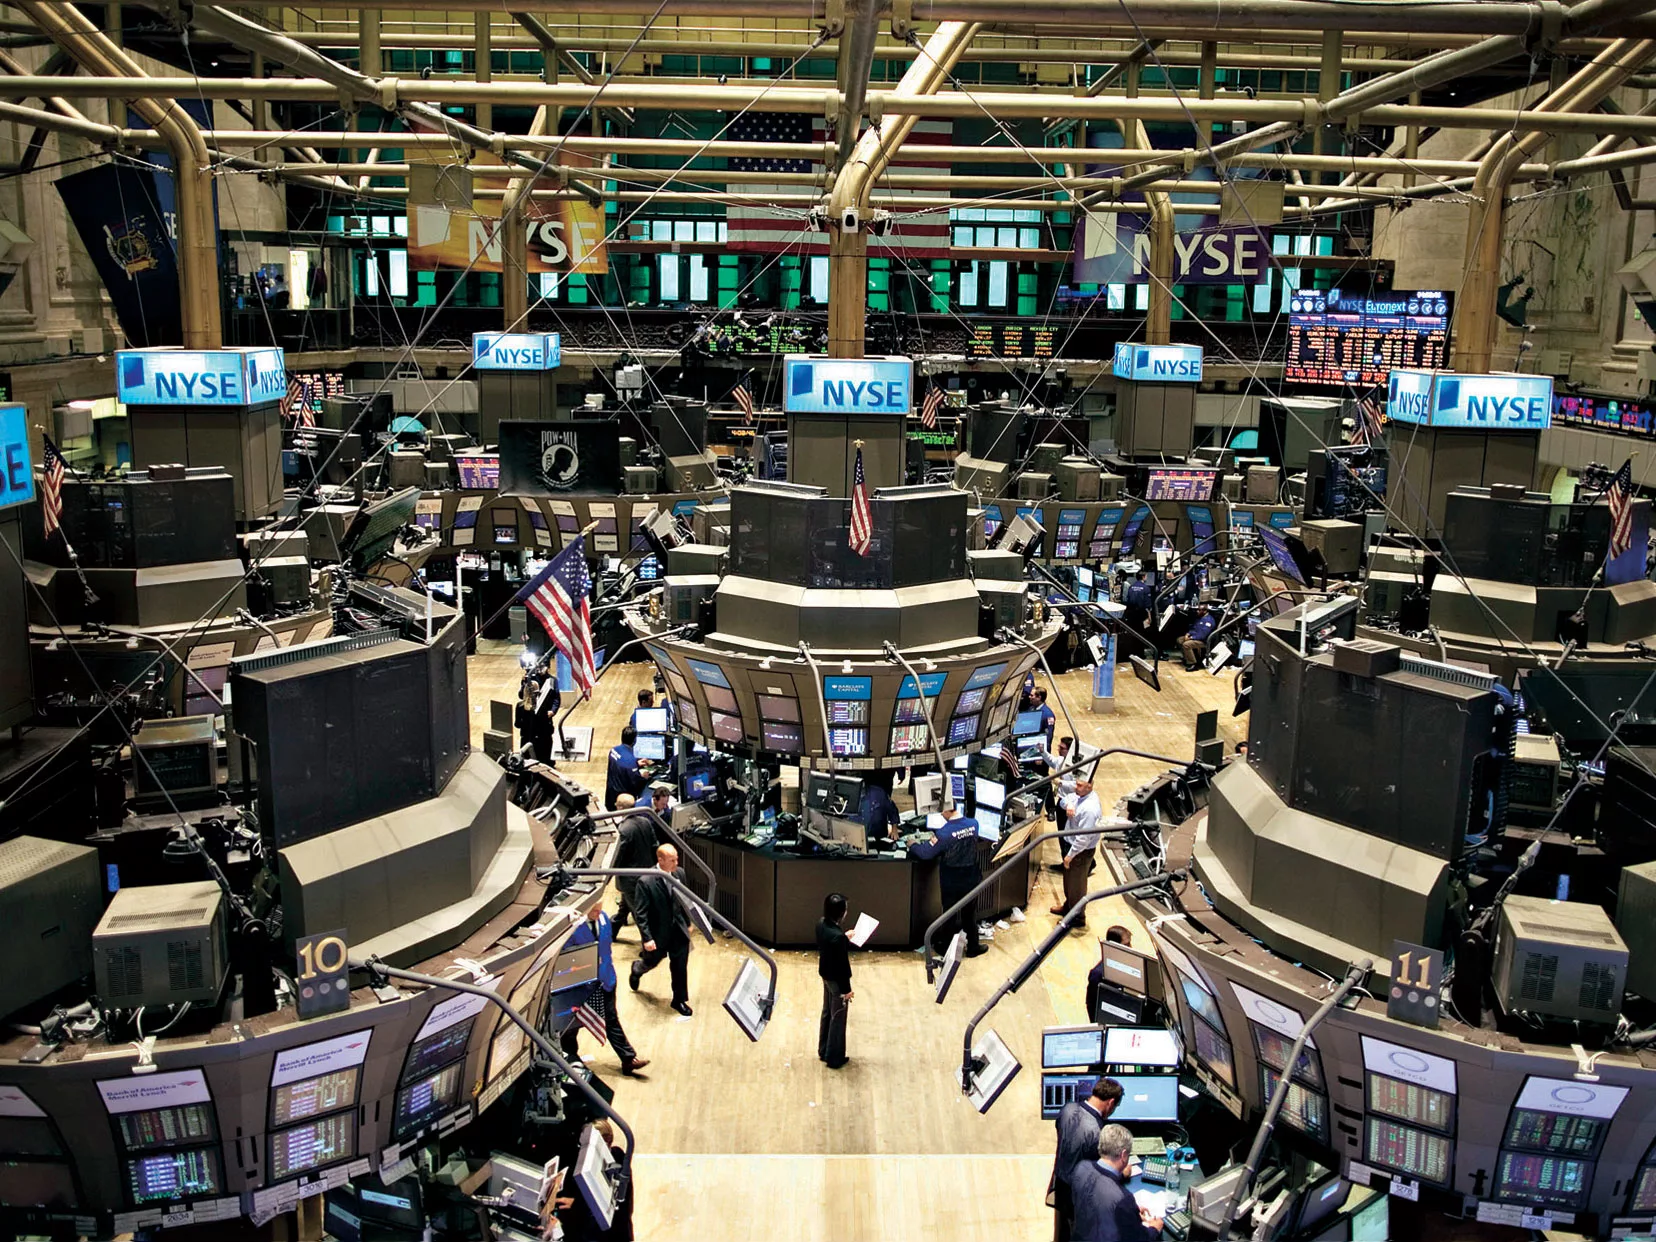
Month and session summary: On August 31, major US indices closed lower, but all three finished August with gains. Nasdaq showed the best monthly performance thanks to demand for AI companies, while the Dow Jones rose for the fifth consecutive month. The energy sector led the day: Halliburton and Valero Energy gained 1.9% due to rising oil prices. Nvidia and chipmakers prevented a deep Nasdaq decline, GameStop rose 2.9%, and PG&E plunged 20.1% due to wildfire risks in California.
Expectations: The probability of a 25 bps Fed rate hike in September exceeded 65% following Kevin Warsh's hawkish speech in Jackson Hole. Before the September 1 open, futures are near neutral ahead of labor market and ISM data.
Europe and Asia: Oil, Inflation, and IPO Launches
Europe: The STOXX 600 lost 0.6% (to 651.1), and the DAX fell 1.2% due to rising inflation in Germany to 2.9% and a jump in energy inflation to 10.5%. Gas prices ended summer at 3.5-year highs, and storage levels are depleted. The ECB is close to a rate hike in September.
Asia: The Nikkei 225 trades flat, the Hang Seng loses 1%, and Shein shares plunged 8% on their first day of trading in Hong Kong due to slowing growth. Economic data is strong: China's private PMI rose to 51.5, Japan's PMI to 54.9, and South Korea's exports jumped 68.7%. Strong demand for chips and AI equipment is currently restrained by high rates and oil prices.
Oil: Brent Holds Above $91 per Barrel
Dynamics: Prices are rising for the second session in a row: Brent at $91.15 (+0.7%), WTI at $86.46 (+0.8%) after nearly a 3% jump the day before. Strikes between the US and Iran and threats from Donald Trump have increased risks to Persian Gulf infrastructure.
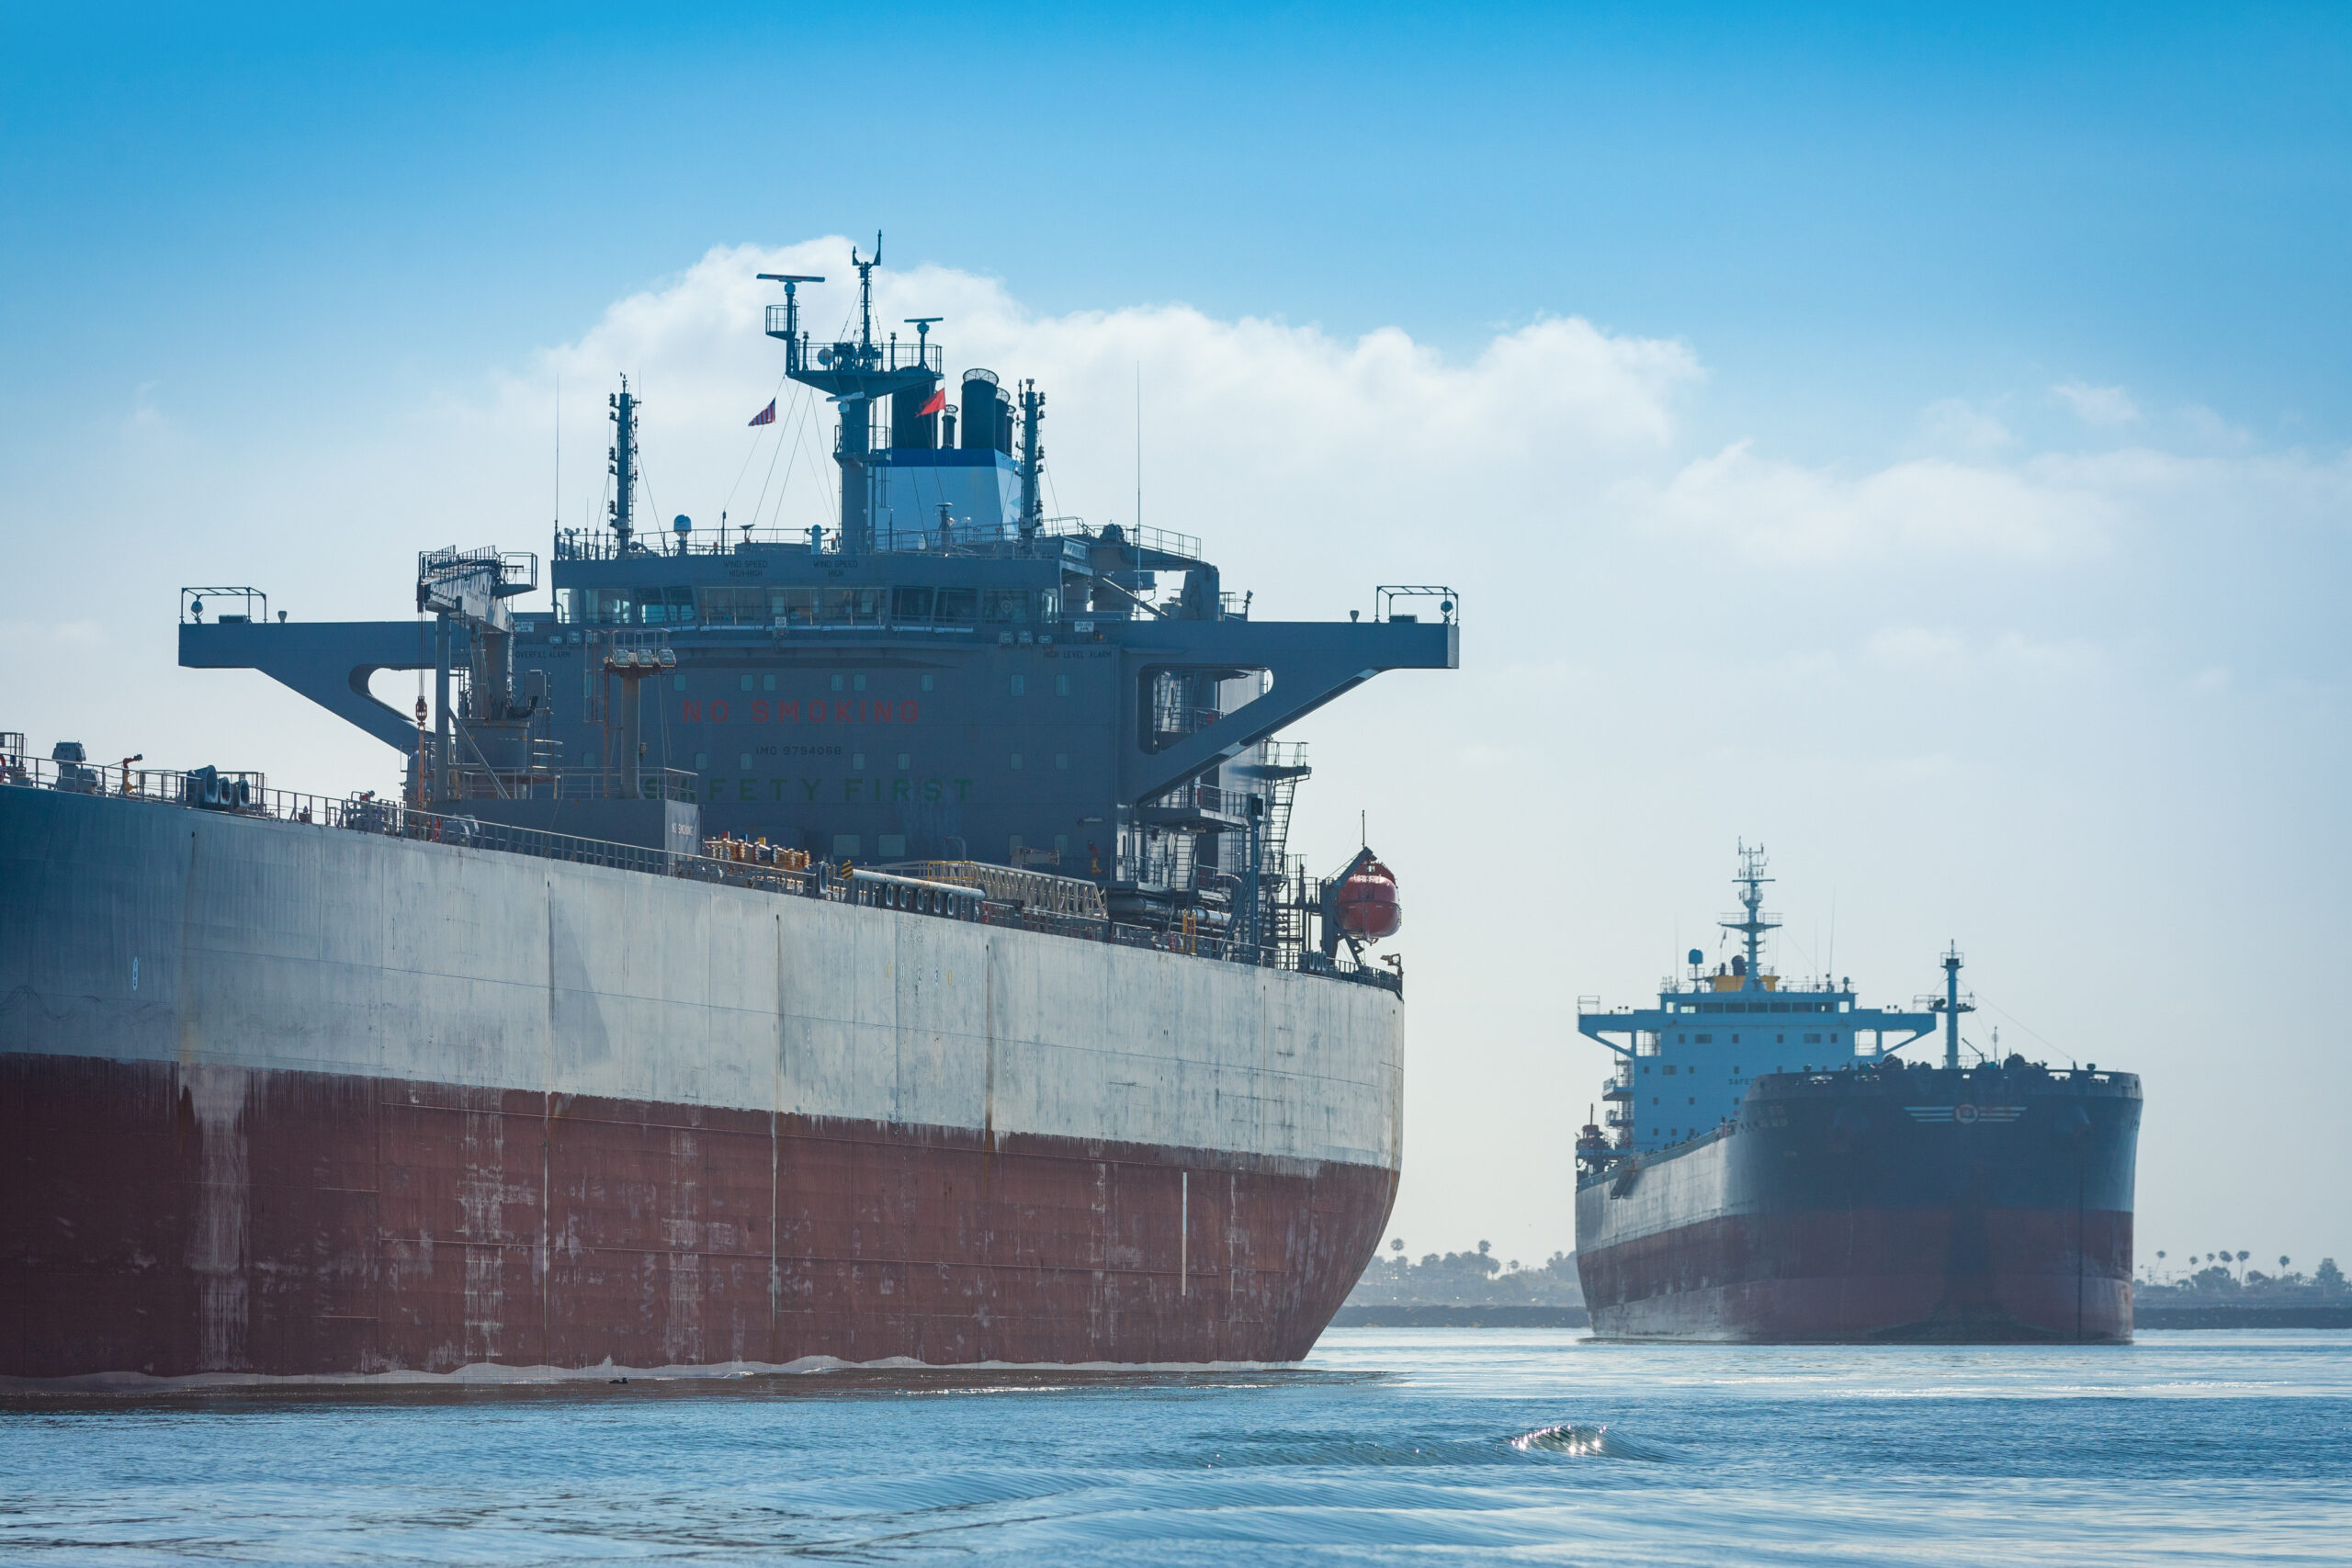
Strait crisis: On Monday, only 5 cargo ships (excluding liquid fuel tankers) passed through the Strait of Hormuz out of the usual 14; one tanker was hit by 3 shells. The US strategic reserve fell to 286.6 million barrels, depriving Washington of intervention levers. Escalation could instantly push oil to $95–100.
Bonds, Currencies, Precious Metals, and Cryptocurrencies
Debt market and currencies: The yield on 10-year US Treasuries rose to 4.78% (the highest since January 2025). Japan's 10-year bonds rose to 3% for the first time since 1996 amid a 73% probability of a BOJ rate hike. The dollar is strong: DXY at 99.51, EUR/USD at 1.1605, USD/JPY holding around 159.8.
Gold and Bitcoin: Gold fell to $4,428.54 (-0.4%), yielding to high bond yields. Bitcoin trades in the $78,400–78,800 range, closing August with a 24% gain (the best month since November 2024). Support at $77,000 protects the market from dropping to $74,000–75,000.
Main Events of the Week:
Today at 19:00 ALMT, ISM indices, JOLTS job openings, and construction data will be released. The week's highlight is the US August labor market report on Friday, September 4 (17:30 ALMT).
| Time / Date | Event |
|---|---|
| 19:00 ALMT (Sep 1) | US PMI, ISM index, industrial orders, and JOLTS |
| September 1 | Preliminary Eurozone inflation estimate for August |
| 17:30 ALMT (Sep 4) | US Labor Market Report (Non-Farm Payrolls) from BLS |
Summary: September begins under the influence of a "volatile mix": oil above $91, rising inflation expectations, and a global sell-off in government bonds pushing yields higher. Steady demand for AI components supports Asia's industry, but the market direction will be determined by energy prices and interest rates. Escalation near the Strait of Hormuz could push Brent to $95–100, while Friday's US employment report will either cement 10-year US Treasuries yields above 4.75% or restore demand for growth stocks and gold.